A new pan-India survey puts hard numbers behind what IRDAI has been saying for weeks: the insurance distribution system has a trust problem, and agents are at the centre of it.
The study, titled “India’s One-Hour Insurance Problem” and conducted by Upstox in collaboration with Fingrowth Media, surveyed 450 individuals and held qualitative discussions with 300 participants across 20 cities. Agents from India’s top 10 life insurers were part of the sample. Among respondents, 93% owned endowment or ULIP products.
The one-hour problem
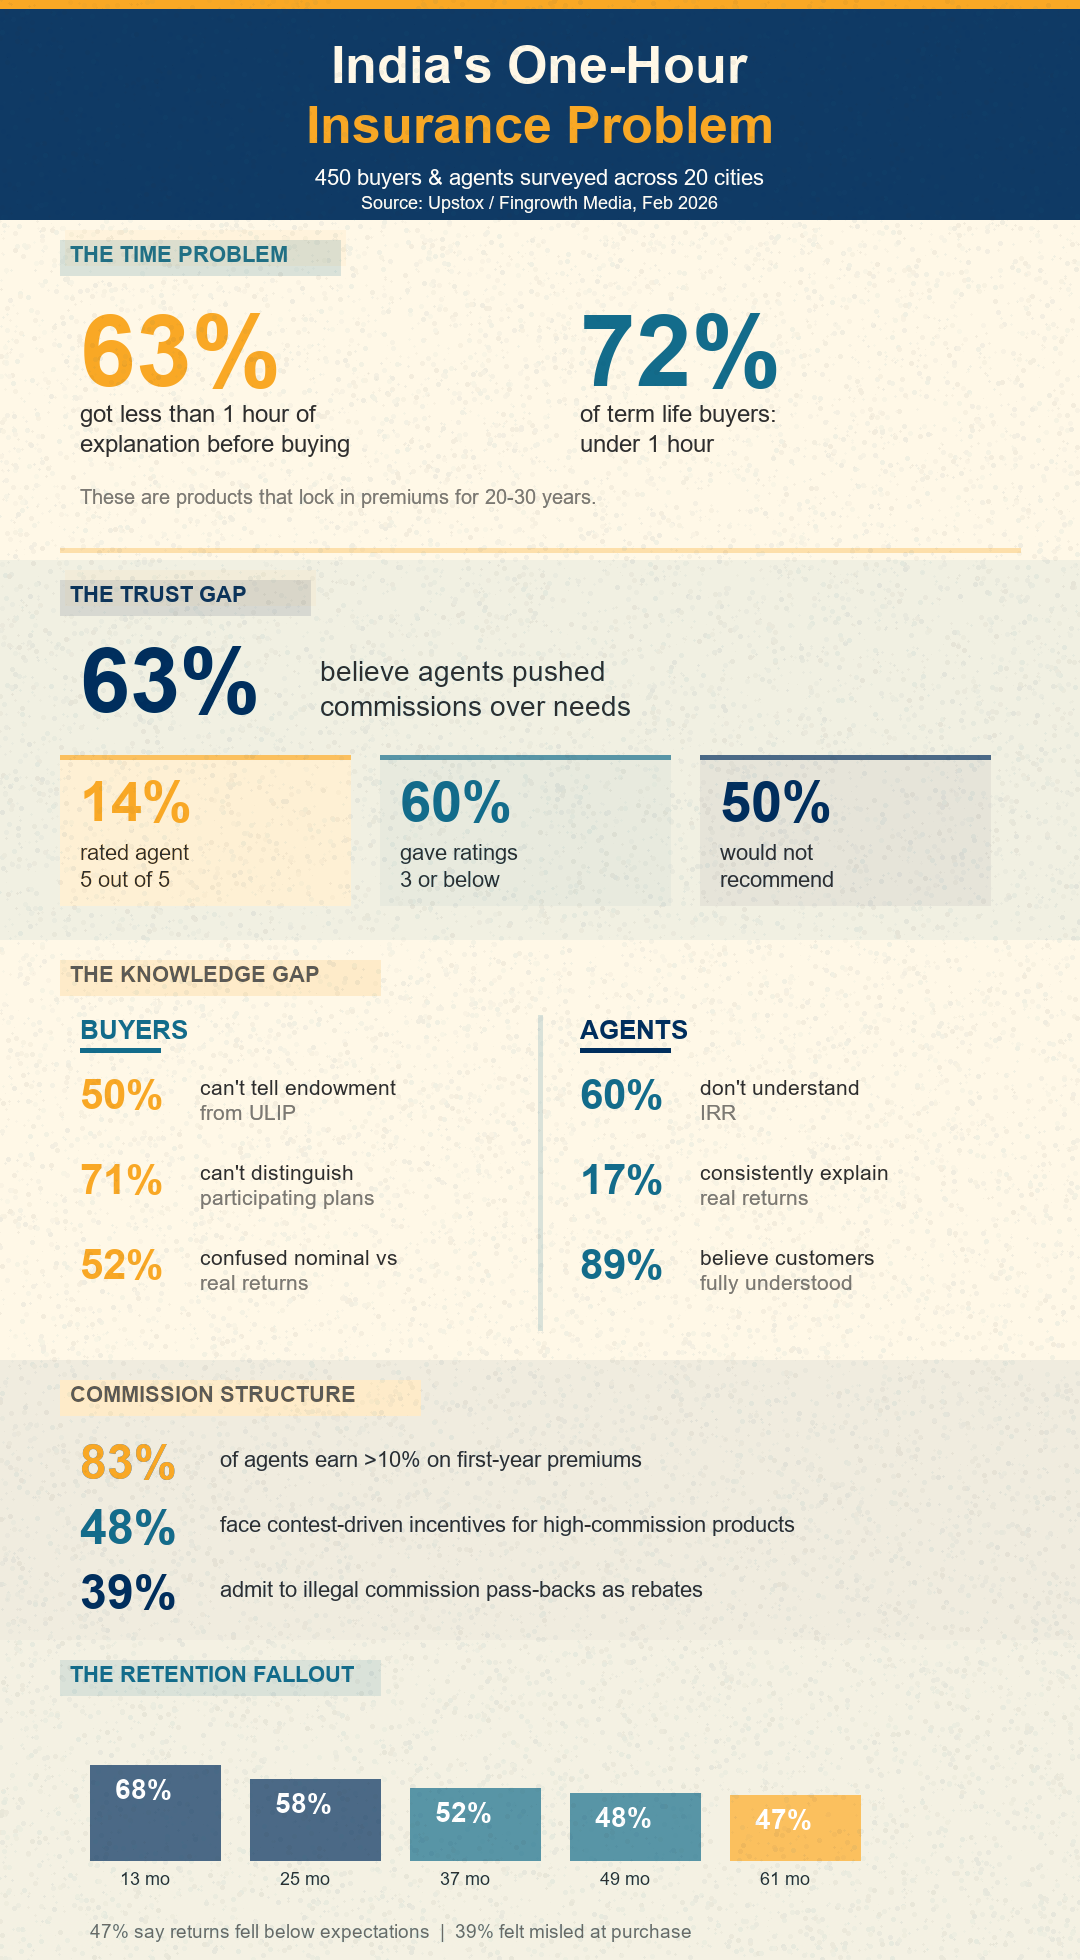
The headline finding: 63% of buyers received less than one hour of explanation before committing to multi-year life insurance policies. For term life insurance, the number was worse: 72% said the conversation lasted under an hour. These are products that lock in premiums for 20 to 30 years, yet the average sales interaction barely covers the basics.
Did You Know: 72% of term insurance buyers in this survey spent under an hour deciding on a policy they’ll typically hold for 20 to 30 years.
Half the respondents could not distinguish between endowment and ULIP policies despite owning one. 71% could not tell a participating plan from a non-participating one. 52% confused nominal returns with inflation-adjusted returns. The knowledge gap is not surprising when agents themselves struggle: 60% of surveyed agents did not fully understand Internal Rate of Return (IRR), and only 17% consistently explained real returns to buyers.
Commissions first, customers second
63% of buyers said they believed their agent prioritised personal commissions over their needs. The agent data backs this up. 83% of agents earned over 10% commission on first-year premiums. 48% reported contest-driven incentives that steered them toward high-commission products. 39% admitted to commission pass-backs as rebates, a practice that is illegal under IRDAI regulations.
Watch Out: Commission rebates — where an agent passes back part of their commission as a cashback or discount — are illegal under IRDAI rules. If an agent offers one, treat it as a warning sign about how they’re advising you.
Trust scores reflected the damage. Only 14% of buyers rated their agent 5 out of 5. A full 60% gave ratings of 3 or below. Half said they would not recommend their agent to anyone.
The retention fallout
The consequences show up in lapse data. Industry retention drops from 67-70% at 13 months to 45-49% at 61 months. Nearly half of all policyholders walk away within five years. 47% of respondents in the survey said actual returns fell below expectations; 39% felt misled or under-informed at the time of purchase.
Fact: Industry data shows nearly half of all policyholders lapse their policies within five years — the clearest sign that many policies are sold on commission pressure, not genuine need.
Why this matters now
This data lands at a pointed moment. Just yesterday, IRDAI Member Deepak Sood told the CII InsureInd conference that high acquisition costs and mis-selling are the two biggest barriers to expanding coverage. The week before, reports surfaced that IRDAI is studying a mutual-fund-style commission cap for insurance distribution.
Sources: Upstox/Fingrowth Media survey (“India’s One-Hour Insurance Problem”), Deccan Chronicle, CNBCTV18
Related Reading
- IRDAI Eyes MF-Style Cap on Agent Commissions
- IRDAI: Cut Costs, Stop Mis-Selling to Grow
- Term Insurance Explained for Beginners
Mis-selling leaves a trail in the data
IRDAI persistency data confirms the mis-selling problem. At some insurers, fewer than 1 in 4 policies survive five years. Read the full lapse and persistency analysis | See ombudsman complaint data.
Related reading: IRDAI’s April 2026 commission probe — the regulator is now collecting the data that could reshape agent incentives.